

Xoom: Send Money & Transfer
by Xoom, a PayPal Service
4.8
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.8
- Price
- Free
- Download
- 5.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
Sending money across borders is one of those tasks that looks simple until you have to do it quickly, from a phone, with the right recipient details and a clear idea of the final cost. I spent time using Xoom: Send Money & Transfer as a finance app, and my overall impression is that it is built for people who want an international transfer process that feels guided rather than improvised. It is free to download, the developer is Xoom, a PayPal Service, and its age rating is Everyone, so it is approachable for ordinary household use.
The app supports transfers to Mexico, India, and many other destinations, covering 145 countries in total. That wide reach is useful, but the real value is not simply the number of destinations. It is the way the app keeps the transfer centered on a few practical questions: who is receiving the money, how will they get it, how much will arrive, and what information is needed before the transaction can move forward.
How I use the basic transfer workflow
My preferred starting point is deliberately slow. I choose the destination first, enter the amount, and then review the available delivery method before filling in every recipient detail. This order matters because international transfers can change depending on the country and the way the recipient collects the money. Beginning with the destination gives me a clearer picture of the path I am taking instead of treating every transfer as identical.
For a first-time transfer, I would have the recipient’s legal name, contact information, and any details requested for the selected delivery option ready before opening the app. That small preparation step prevents the most common kind of friction: stopping halfway because the person receiving the money does not have the information needed to complete the transaction. It also reduces the chance of entering a nickname or shortened name when formal details are required.
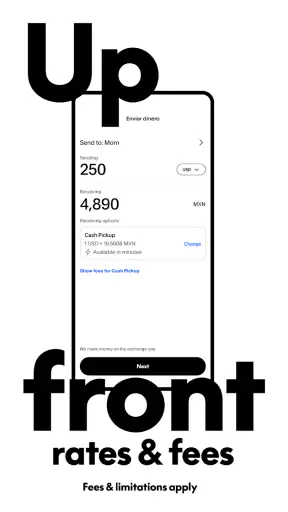
The amount screen deserves more attention than a quick glance. I check the amount I am sending, the amount the recipient should receive, the exchange rate shown, and any applicable charge before confirming. The important figure is not just what leaves my account, but what reaches the other person. A transfer can look inexpensive at first while producing a different result once currency conversion and delivery choices are considered.
In an everyday situation, imagine sending money to a family member who needs help with a bill. I would set aside the recipient’s details, open the app, select the country, enter the intended amount, and pause at the final review screen. I would then message the recipient separately to confirm the name and delivery method. That extra check is more useful than rushing through a familiar-looking form, especially when the transfer cannot easily be corrected after submission.
The guided flow is one of the app’s strongest qualities. It is less intimidating than arranging an international payment through a general banking interface, where transfer terminology and destination requirements may be scattered across several screens. Xoom keeps the task focused. I do not need to understand every part of international payments to begin, although I still need to read the final summary carefully.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
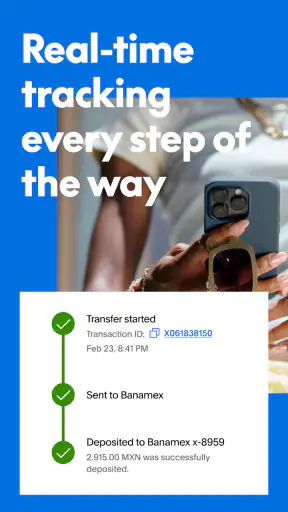
Tracking is also part of the practical experience. After sending money, I want a clear way to revisit the transaction and understand where it stands. I treat the confirmation information as something to save, particularly when the recipient is waiting for the transfer or when I am sending money for a time-sensitive expense. I would not rely on memory or assume that a completed submission means the recipient has already collected the funds.
Settings I would check before sending regularly
People who use the app repeatedly should spend a few minutes reviewing their account and notification preferences instead of treating the first successful transfer as the end of the setup process. I look for the options that affect how I receive updates, how my personal details are displayed, and how easily I can review past activity. The exact choices available can depend on the account and destination, so I prefer to inspect the screens directly rather than assume that every user sees the same controls.
Notifications are especially useful when a transfer has several stages. I would keep relevant status updates enabled if I regularly send money to someone who is waiting for it, but I would avoid allowing sensitive information to appear openly on a lock screen. A better habit is to use notifications as prompts to open the app and inspect the transaction, rather than treating a short alert as the complete explanation.
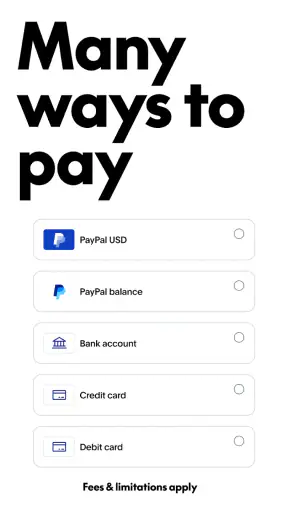
I also check the funding method before starting a transfer. If the app presents more than one way to pay, I compare the final result rather than selecting the first familiar option. The most convenient funding choice is not automatically the best one for every situation. A person sending a small amount occasionally may value simplicity, while someone supporting family every month may care more about predictable costs and a repeatable process.
Another worthwhile setting is the device’s own security. I keep the phone protected with a screen lock and avoid starting a transfer on a shared device. The app handles financial information, so basic phone security is part of using it responsibly. I also avoid saving recipient details casually in notes or messages where they could be exposed. Convenience should not turn into a collection of sensitive information scattered around the phone.
One setting-related habit I recommend is checking the app version before a planned transfer. The current version is 10.11.0, and keeping a finance app reasonably current helps avoid a situation where an old installation behaves differently from the screens described in current help material. I would update before an urgent transfer, not five minutes before a deadline, because any app update can require a fresh sign-in or a quick review of the interface.
Faster patterns that still leave room for checking
Once I know the destination and recipient details are stable, I can make the process faster without becoming careless. My repeatable routine is to confirm the recipient’s legal name first, select the country, enter the amount, compare the delivery choices, and read the final summary aloud in my head. That last step sounds excessive, but it catches mistakes better than tapping through familiar screens automatically.
For recurring support, I keep a private checklist outside the app rather than repeatedly searching through old conversations. It contains the recipient’s preferred name format, destination, usual delivery method, and the questions I need to confirm before sending. I do not store passwords or unnecessary financial information there. The purpose is to make the workflow consistent, not to create another security risk.
A second useful pattern is separating “planning” from “sending.” I first open the app to see the current conversion and delivery information, then decide whether the transfer still makes sense. If the recipient needs a specific amount in their currency, I work backward from that target and review the amount the app calculates. This is more reliable than deciding on a round number in my own currency and assuming the recipient will receive the intended sum.
I also avoid sending several transfers in a rush just because the first one appears to be moving normally. If I need to support more than one person, I complete and review each transaction separately. That creates a clear record and makes it easier to identify which recipient or amount needs attention. It may take a little longer, but it is safer than mixing names and amounts across a batch of hurried confirmations.
Another practical shortcut is preparing the recipient for the next step. I tell them which name I used, what delivery method to expect, and that they should contact me if the information does not match their identification or collection details. This reduces back-and-forth messages after the transfer and helps expose a mistake early. The app can guide the sender, but it cannot replace communication with the person receiving the money.
These habits are where the app becomes more useful for experienced users. There is no need to invent a complicated system around it. The gains come from consistent preparation, careful review, and using the same sequence every time. I find that approach faster in the long run than trying to discover a new shortcut during an urgent transfer.
Where the convenience has limits
Xoom is not a universal answer for every kind of payment. It is designed around sending money internationally, so I would not choose it for ordinary local payments, casual splitting of a restaurant bill, or moving money between my own accounts when a domestic banking tool is simpler. Its value appears when the recipient is in another country and the transfer path needs to account for currency and local delivery options.
I also would not assume that every destination works in exactly the same way. Country-specific requirements, delivery methods, verification steps, and availability can affect the experience. The broad destination coverage is impressive, but it should not be interpreted as a promise that one workflow fits Mexico, India, and every other supported country. Before promising someone a particular delivery method, I check what the app actually presents for that destination.
Speed should be treated carefully as well. The app is designed to make transfers convenient and can provide status information, but the recipient’s actual access may depend on the selected method and circumstances outside the app. If money is needed for an immediate emergency, I would not send it at the last possible moment and assume the transfer will be available instantly. I would build in time for review, verification, and collection.
Verification can also be a point of friction. Financial services need to confirm identity and transaction details, and a user who wants a completely anonymous or paperwork-free experience is likely to be disappointed. I see this as a reasonable trade-off, but it means the app is not ideal for someone unwilling to provide the information required to use a regulated money-transfer service.
Cost comparison is another area where experienced users should remain alert. I compare the recipient’s final amount and the total cost with the usual alternative, such as a bank’s international transfer service or another remittance app available in my region. A bank may be more familiar for large, formal transfers, while a competing remittance service may be better for a particular corridor or funding method. Xoom’s strength is the focused mobile flow, not an automatic guarantee that it will be the cheapest option for every route.
There is also a human limitation: the sender remains responsible for entering correct information. A polished interface cannot protect me from choosing the wrong person with a similar name, entering an incorrect phone number, or selecting an unsuitable delivery option. I treat the review screen as a control point, not as a formality. If anything looks unfamiliar, I stop and verify it before continuing.
Who will get the most from it
I think the app is a strong fit for people who send money to relatives abroad, support someone studying or working in another country, or make occasional international transfers without wanting to visit a branch. It is also useful for senders who value a clear mobile process and want to check transaction progress from the same place where the transfer began.
It suits both occasional and recurring users, but the recurring user benefits most from building a disciplined routine around it. Keeping recipient details accurate, checking the final amount every time, and reviewing notifications makes the app feel much more dependable than simply tapping through a familiar sequence. The fact that it is free to download lowers the barrier to trying it, although the transfer itself still needs to be evaluated on its displayed terms.
I would suggest a different option to someone who only makes domestic payments, needs sophisticated business payment controls, or prefers managing all finances through an existing bank relationship. A bank may offer better integration with accounts and records for certain users. Likewise, someone who prioritizes the absolute lowest total cost should compare alternatives for the exact destination and amount instead of choosing based only on brand familiarity or convenience.
The app’s public reception is encouraging: it holds a 4.8 average from around 363 thousand ratings, with more than 5 million installs. Those figures suggest that it has become a familiar choice for a large audience, but they do not remove the need to check the details of an individual transfer. A popular service can still be the wrong fit for a specific country, recipient, or payment situation.
My verdict after building a repeatable routine
What I like most is the balance between a guided experience and enough information to make a sensible decision. Xoom does not require me to turn an international transfer into a research project, yet it gives me useful checkpoints for the destination, amount, delivery method, and transaction status. For a friend who regularly sends money abroad and wants a phone-first workflow, I would recommend trying it.
My recommendation comes with one condition: do not confuse an easy interface with a transfer that needs no checking. I would verify the recipient, compare the final amount, inspect the available delivery option, and allow time for any required review. Those habits are more important than finding a hidden shortcut, and they make the experience noticeably safer and less stressful.
After its release on August 8, 2012, the service has had time to become a recognizable name in mobile remittances, and the current app reflects that mature, task-focused approach. It is not the right tool for every financial movement, but it is a practical choice when the job is sending money across borders from a mobile device.
My final view is simple: use it when international sending is the problem, prepare the recipient details before opening the app, and judge each transfer by what the recipient will actually receive. With that mindset, Xoom feels less like a one-tap promise and more like a dependable routine for a real-world financial task.
Pros
- Fast international transfers to many destinations
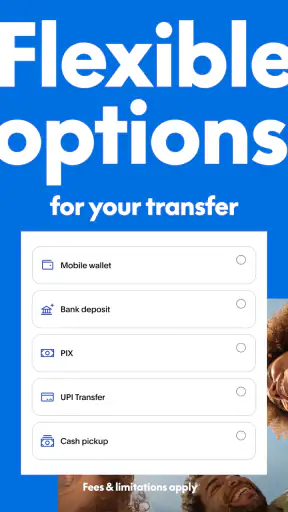
- Supports bank deposits, cash pickup, and mobile wallets
- Clear exchange rates and transfer fee details
- Reliable service backed by PayPal
- Transfer tracking and status notifications included
Cons
- Fees vary significantly by destination and payment method
- Exchange rates may include a markup
- Some transfers require identity verification
- Delivery times can be longer on weekends or holidays
- Availability of features differs by country
FAQs for Xoom: Send Money & Transfer
What is Xoom: Send Money & Transfer, and what can I use it for?
Xoom is a PayPal service designed for sending money internationally, paying certain bills, and reloading mobile phones in supported countries. From the app, you can choose a destination, enter the recipient’s information, select an available delivery method, and review the total cost before confirming. Available services vary by country, so it is important to check whether your destination and preferred payout option are supported.
How much does Xoom charge for an international money transfer?
The cost of a Xoom transfer depends on several factors, including the sending country, destination, transfer amount, payment method, currency conversion rate, and delivery option. The app normally displays the fee, exchange rate, and estimated recipient amount before you submit the transaction. Because pricing can change, review the final confirmation screen carefully rather than relying on a general fee estimate found elsewhere.
How long does a Xoom transfer take to arrive?
Transfer speed depends on the destination, payment method, recipient’s bank or pickup location, local holidays, verification requirements, and the selected delivery option. Some transactions may arrive quickly, while others can take longer if additional checks are needed. Xoom provides an estimated delivery time during checkout and usually lets you track the transfer status in the app using the transaction details.
What information or documents are required to send money with Xoom?
You generally need to create or sign in to a Xoom account and provide accurate personal information, payment details, and recipient information. Depending on the transaction, amount, destination, or regulatory requirements, Xoom may request identity verification or additional documentation. Enter names exactly as they appear on the recipient’s official identification or bank account to help prevent delays, rejection, or pickup problems.
Is Xoom safe, and what should I check before confirming a transfer?
Xoom uses account security measures and transaction monitoring, but users should still protect their login details and verify every transfer carefully. Confirm the recipient’s name, phone number, bank or pickup information, destination country, exchange rate, fees, and delivery estimate before sending. Never transfer money to someone you do not trust, and contact Xoom support promptly if you notice suspicious activity or an incorrect transaction.

Xoom: Send Money & Transfer
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via product.feedback@xoom.com, visit http://www.xoom.com, or review their https://www.xoom.com/privacy.










